
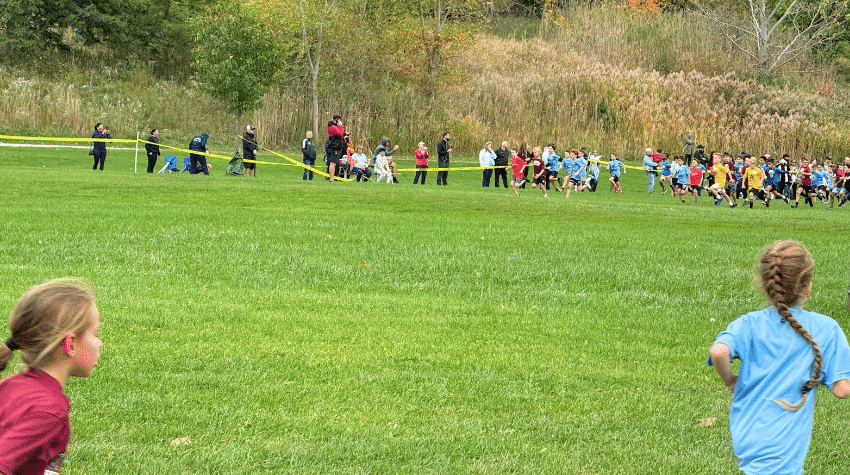
And they’re off.
The elementary school cross-country meet was yesterday.
I used to joke that it’s the most unproductive day in Windsor-Essex. Half the region’s parents take the morning off or sneak out of meetings to watch their kid cross a finish line.
I stand corrected.
I ran into more clients, colleagues, and people I’d been meaning to call than I do at most networking events. Conversations happened. Follow-ups got scheduled.
Business got done.
Win for the kids. Win for the parents pretending they’re just there to cheer.
The other thing that got me: the crowd. There had to be hundreds of parents there.
When I ran cross-country in elementary school, I honestly don’t remember a single parent showing up. I’m not even sure my parents knew I was on the team.
Things have changed. Showing up is the expectation now.
In more ways than one.
Ontario’s financial regulator — FSRA — has been quietly making moves in the private mortgage space this year.
Earlier in 2026, they moved to revoke the licence of a mortgage administrator called Flex Home Loans. The owner was penalized, barred from the industry, and investors were left scrambling to transfer their files to a licensed administrator.
The reason: the firm had been lending money outside a licensed entity — roughly $7.6 million across 244 mortgages. Borrowers received no proper disclosure. No suitability assessment was done. And the owner made false declarations on his licence renewal forms for two consecutive years.
FSRA also reported 100 enforcement actions in their last fiscal year. Up from 65 the year before.
They are not slowing down.
For anyone who has been following this newsletter over the past few weeks, this is relevant.
We’ve talked about private mortgage lending as an alternative fixed income investment. We’ve talked about the returns. We’ve talked about the risks.
This is what the risk looks like in practice.
When a mortgage administrator loses its licence mid-cycle, investors don’t just lose a service provider. They lose oversight of their capital. Their files need to move. The process is disruptive, sometimes costly, and sometimes too late to prevent real losses.
The investment itself — the mortgage, the security on the property — doesn’t disappear. But who is watching it matters enormously.
There are not many licensed mortgage administrators in Windsor-Essex.
Unimor Capital has been licensed since 2008. We’ve been through rate cycles, defaults, power of sale situations, and two significant economic disruptions. The licence isn’t a formality. It’s what keeps investor capital properly managed and protected.
FSRA tightening enforcement is, honestly, good news for investors who are already working with the right people.
It means the gap between credible operators and everyone else is getting harder to ignore.
If you’re putting capital into private mortgages — or thinking about it — ask who is administering the file. Ask how long they’ve been licensed. Ask what their process looks like when a borrower stops paying.
Those questions have answers. Make sure you like them before you commit.
Until next week,
Vince
P.S. Two of my three kids ran. Both finished strong. My oldest has officially retired from cross-country at age 12. I told her she’s got time to reconsider. She disagrees.