
Soccer tryout season is upon us.
All three of my kids were in the mix this week. Same week. Different fields. Different times.
I’ll be honest — tryout season is a lot. The logistics alone deserve their own newsletter.
But the part nobody tells you about is how hard it is to stand on that sideline and act like you’re not completely invested in every touch, every run, every decision your kid makes out there.
Casual. Relaxed. Just a dad watching some soccer. Definitely not internally coaching every play.
That was me this week. Three times.
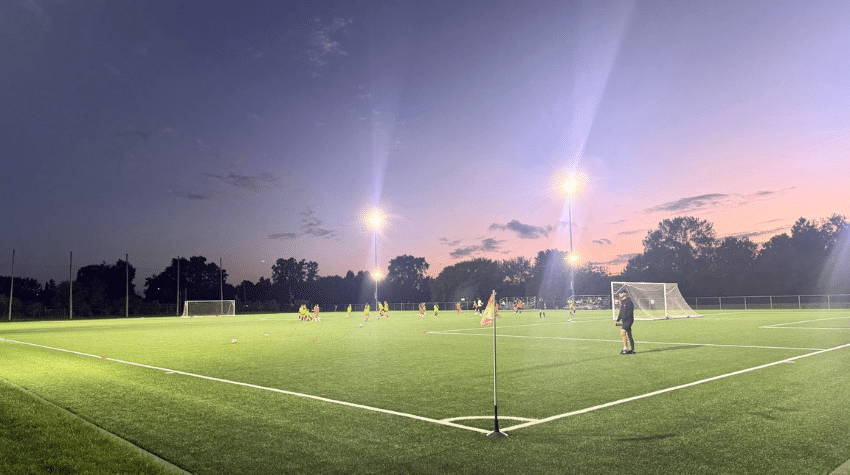
I was watching my daughter’s tryout when the sun started going down and the field lights came on.
And just like that — I was 16 again.
Night games were always the big ones when I was growing up. The ones you looked forward to all day. The ones where the atmosphere was different and everyone felt it.
Standing there in my very calm, very relaxed dad stance, something about those lights just got me. I pulled out my phone and took a picture.
A grown man. Photographing a soccer field. No apologies.
All three kids did well. I couldn’t be prouder.
The lights, the field, the memories — that’s what I’ll carry from this week.
Over the past several weeks I’ve been building toward a question worth answering directly.
Where should your money be working?
We’ve talked about dollar devaluation. The shift from labour to capital. The September reset.
Now let’s get specific.
But first — something worth naming.
Most people make investment decisions from an incomplete menu.
Not because they’re not smart enough to understand their options. But because the people who typically give financial advice — banks, financial advisors, insurance companies — have a natural incentive to show you what they sell.
And what they sell is usually a version of the same conventional options.
Savings accounts. RRSPs. Mutual funds. GICs. The stock market.
Nobody sits you down and walks you through everything available to you. That conversation doesn’t happen on its own. You have to go looking for it.
So let’s look.
Savings accounts and GICs are returning somewhere between 3% and 4% in Canada right now.
With inflation running above that and the dollar quietly losing purchasing power every year, you’re not getting ahead. You’re slowing down how fast you fall behind. That’s not the same thing.
The stock market offers better long term returns historically. But it comes with volatility most people underestimate until they’re living through it. And for anyone who needs predictable income rather than growth over a 20-year horizon, it’s an uncomfortable fit.
Real estate is still a good long term asset. But the entry cost is high, it’s illiquid, and managing a property is its own job.
There are also non-passive options that don’t get talked about enough.
Investing in yourself. Buying into a business. Building a side income. These can generate exceptional returns — but they require your time, your energy, and your attention. For someone already working hard and looking for their capital to do some of the lifting, that matters.
So where does that leave people who want their money working harder, want predictable returns, and don’t want to be glued to a stock ticker or manage a rental property?
This is where alternative fixed income investments come in.
A category most people have never been introduced to — not because it doesn’t exist, but because nobody showed them the full menu.
One option within that category — and one I work with directly — is private mortgage lending.
Here’s the simple version.
A borrower needs financing that traditional banks won’t provide or can’t move fast enough to provide. A private lender steps in and provides that capital, secured against real estate. The lender earns interest on that capital for the term of the mortgage.
Returns typically range between 8% and 12% annually depending on the deal, the term, and the position.
That’s significantly above what a GIC or savings account is offering. And unlike the stock market, the return is contractual and predictable.
This isn’t for everyone. Private mortgage lending comes with its own risks and requires proper due diligence and administration.
But for the right investor — someone with capital to deploy, looking for income rather than growth, who wants security behind the investment — it’s worth understanding.
Over the next few weeks I’ll share more about how this works, what to look for, and what questions to ask.
For now, just know the option exists.
And that your money has more choices than the bank is probably showing you.
Until next week,
Vince
P.S. The sunset in that photo was real. So was the smile on my face watching my kids out there. Some things don’t need a filter.