
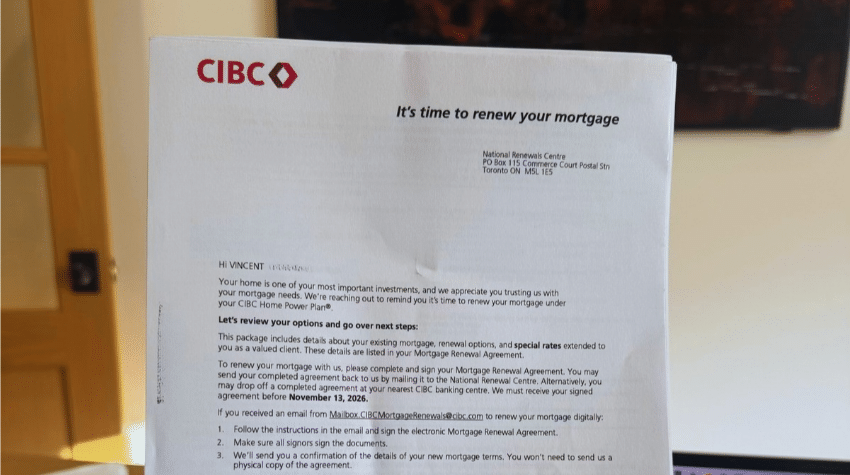
The renewal letter arrived for one of my rental properties a few weeks ago.
Three options. Tidy little boxes. Sign here.
I set it aside.
Not because I was busy — because the rates were bad. Depending on the term, the rates they offered me were up to 0.65% higher than what’s actually available in the market right now.
That gap is not an accident. Lenders send renewal offers knowing that a meaningful percentage of borrowers will just pick one and sign. It’s easy. It feels like the path of least resistance.
It costs real money.
On a $400,000 mortgage, 0.65% is $2,600 a year. Over a five-year term, that’s $13,000 left on the table. For doing nothing.
So, I’m shopping my own renewal. And the decision I’m sitting with right now is the same one a lot of borrowers are facing: fixed or variable.
It’s not a simple call. Not right now.
Here’s what’s happening in the rate environment at the moment.
Fixed rates have already moved — and most people missed it. The Bank of Canada hasn’t touched its rate yet, but the lowest five-year fixed jumped roughly 40 basis points in a single month. Fixed rates follow bond yields, not the BoC.
Bond yields have been climbing globally, driven by heavy government borrowing and oil price pressure. The banks absorbed some of it to stay competitive on renewals. But the rate is up.
Variable rates are likely moving too. The Bank of Canada meets October 28th.
Multiple economists who were calling a hold have revised to a hike in the last few days. I’ve been watching the signals and I think they move. If they do, prime goes up and variable rate borrowers feel it immediately.
So, the question isn’t just fixed vs. variable in the abstract.
It’s: is the discount you’re being offered on a variable rate large enough to absorb a rate hike — or two — and still come out ahead?
That math looks different today than it did six months ago.
The other thing worth knowing: lenders pass rate increases through faster than they pass decreases. When rates drop, they move slowly. When rates rise, the adjustment is quick. That asymmetry matters when you’re deciding how much risk you want to carry.
I’m still working through the numbers on my own property. I know how I’m leaning, but I haven’t signed anything yet.
If you have a renewal coming up — or you’re just trying to make sense of what’s happening with rates right now — I’m happy to walk through how I’m thinking about it.
No obligation. Just a conversation.
Until next week,
Vince
P.S. The renewal letter is still sitting on my desk. The lender hasn’t followed up once. That tells you everything you need to know about whose interests they’re looking out for.
Have Capital Available? Let’s Put It to Work