
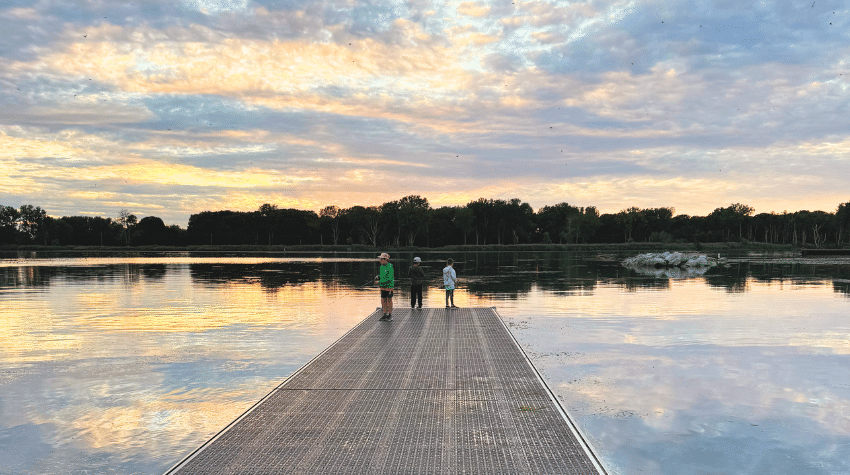
My son has discovered fishing.
Not just discovered it. Become completely consumed by it.
He’s been bugging me to go every night. His friends are the same way. Something about kids aged 7 to 12 and a fishing rod right now — I don’t know what it is, but they can’t get enough.
This past Friday we made it happen.
A few of his buddies, their dads — who happen to be good friends of mine — and a perfect fall evening on the water.
The kids fished. The dads untangled rods, told bad jokes, and had some genuinely good laughs.
At some point I looked up and saw the three of them standing at the end of the dock. I took the picture.
Nobody caught anything worth mentioning. Nobody cared.
We capped the night off with Chinese food and called it one of the better Fridays of the year.
Some of the best nights really are the simplest ones.
Two weeks ago I introduced private mortgage lending as an alternative fixed income investment.
The returns got some attention. 8% to 12% annually tends to do that.
But the question I kept hearing wasn’t about the upside.
It was about the risk.
Good. That’s the right question.
So here’s the honest answer.
Private mortgage lending is not a risk-free investment. No investment is.
The main risk is borrower default. The borrower stops paying, and you have to act on your security.
Acting on your security means power of sale or foreclosure. Taking possession of a property. Managing a process. Eventually selling the asset to recover your capital.
That takes time. It costs money. And it’s not something most individual investors are set up to handle on their own.
This is why administration matters more than almost anything else in private lending.
A mortgage placed properly starts with conservative underwriting. The property value is assessed carefully. The loan-to-value ratio leaves a real buffer. The borrower’s ability to pay is evaluated. The paperwork is done right.
When all of that happens at the front end, a default is manageable. You have real security on a real property. There’s a process to follow. And if the LTV was set correctly, you recover your capital.
Where investors get hurt is almost always one of two things.
The underwriting was poor — too much lent against a property that wasn’t worth it. Or the administration fell apart when things started going sideways.
Those aren’t risks that come with the asset class. They’re execution risks.
Which means who holds and administers the mortgage matters as much as the mortgage itself.
Private mortgage lending, done properly, is a predictable and well-secured source of income.
Done poorly, it’s how people lose money.
The difference is almost always in the details — at the front end, and in who’s watching the file.
More on what that looks like in practice over the next few weeks.
Until next week,
Vince
P.S. My son caught nothing on Friday. He’s already planning the next trip. There’s a lesson in there somewhere about patience and showing up consistently. Probably applies to investing too.